
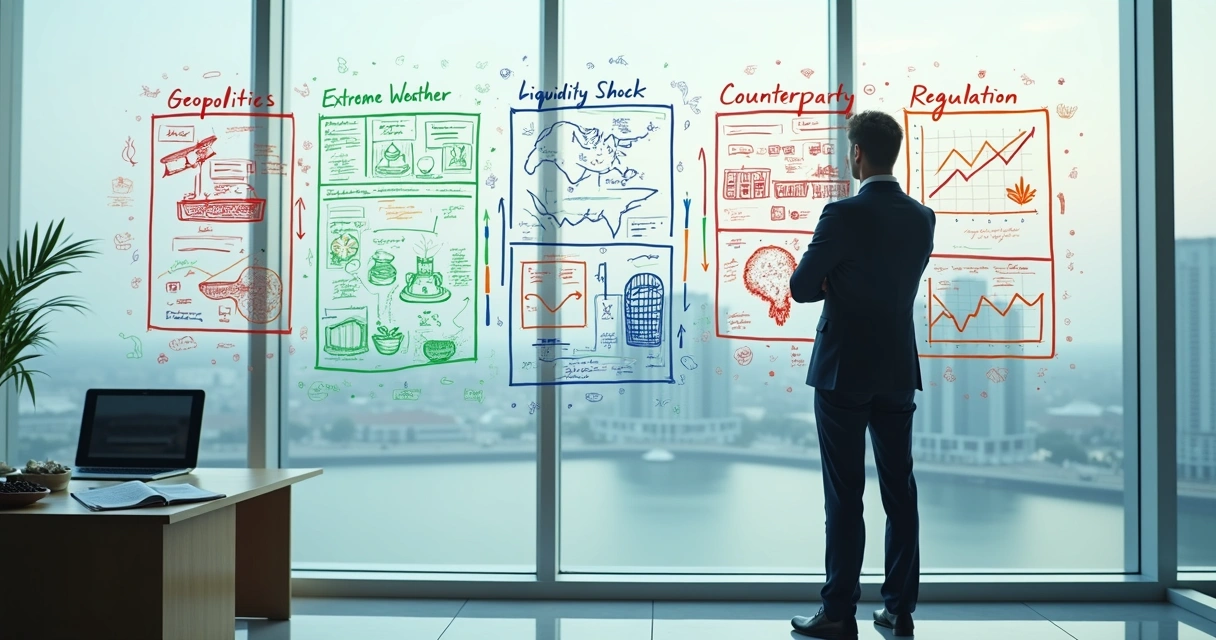
Market turmoil. Weather disasters. Sudden policy changes. Each can upend commodity markets in a single moment. But with thorough preparation, shock need not become crisis. For the agro-financial world—from family businesses to global traders—stress testing is the discipline that sets apart those who survive from those who thrive. Uhedge delivers this edge, uniting physical and financial data, scenario analysis, and advanced models into a single auditable platform.Commodity stress testing is more than a checkbox—it is the pulse-check of an organization’s risk culture and a key to consistent profitability.
Understanding the landscape of commodity risk
The landscape of commodity trading is defined by uncertainty. Prices can spike or collapse with little notice due to events far outside the trader’s immediate control. For grains, coffee, metals, or fuels, volatility is a daily reality. The secret lies not in avoiding uncertainty but anticipating its possible forms and ranges.
Uhedge integrates physical and financial exposures in one environment. As trading has evolved, so too has risk. Gone are the days when spreadsheets and intuition sufficed. Now, commodity trading risk management demands rigorous analytics, intra-day supervision, and rapid response capabilities. The platform at Uhedge was created precisely for these reasons—serving producers, exporters, and financial institutions who can’t afford to be reactive in a world where the next crisis rarely resembles the last.
The purpose and power of stress testing
Every portfolio tells a story. In commodity markets, that story is one of weather, geopolitics, money flows, counterparty trust, and regulatory change. The job of stress testing is to “ask the uncomfortable questions”:
- What if a major trading partner suddenly suspends exports?
- What if a hard freeze destroys a key crop just before harvest?
- How would a sharp drop in liquidity affect open positions and margin calls?
- Could a single counterparty failure ripple through all portfolio exposures?
- What happens if a new regulation forces a rapid revaluation of positions?
Scenario analysis in commodity risk allows organizations to "see around the corner." Rather than react to crisis, they pre-empt and adapt. The value comes not only from identifying vulnerabilities but from quantifying them. Numbers matter, but discipline matters more.
If you only measure yesterday's risks, you will be blindsided by tomorrow's shocks.
What defines a robust commodity stress test?
Commodity stress tests differ from standard risk measures like daily VaR. While VaR estimates the maximum expected loss under regular market conditions, stress tests simulate adverse but plausible events—combining history, expert judgment, and advanced statistics. The effectiveness of any stress testing framework depends on:
- Comprehensive scenario design, reflecting current realities and emerging threats
- High frequency, not just annual or quarterly exercises
- Transparent documentation, suitable for audit and compliance, including IFRS 9 and CPC 38 hedge accounting
- Integration into everyday risk management, not left for “review time”
Five stress test scenarios for market resilience
Uhedge's quantitative methodology, refined by two decades in global finance, supports scenario construction and impact measurement. The following five scenarios reflect the principal categories of risk haunting commodity portfolios today:
1. Geopolitical shock
Few forces shape commodity prices so abruptly as geopolitical events. Sanctions, conflict outbreaks, or trade embargoes can reroute flows of grains, metals, and fuels overnight. Consider the impact of the Russia-Ukraine conflict on global grain prices or trade tensions nudging up fertilizer costs. The point is not only the direct impact but also second-order effects—changing currency valuations, capital flows, and even insurance costs.
In a stress test for geopolitical disruption, portfolio managers might model a sudden closure of key export routes, drastic price divergence between physical and futures, or a currency crisis in a major producing nation. Uhedge’s scenario engine automates the generation of such what-ifs, linking price shocks to margin requirements, liquidity needs, and hedge effectiveness.
Scenario parameters typically include:
- Immediate price shocks for impacted commodities
- Sudden currency deviation impacting export parity pricing
- Incremental increase in volatility and bid-ask spreads
- Changes in basis due to physical vs. futures market dislocation
2. Extreme weather event
No market is more vulnerable to weather extremes than commodities. A severe drought, devastating frost, or sudden floods can wipe out inventories and force rationed deliveries. According to studies on US corn and soybeans between 1995 and 2023, nearly a quarter of all extreme climate events led to substantial abnormal returns in key crops, with extreme temperatures and storms producing the most severe price moves【4:LSU graduate thesis (2024): analyses 1995–2023 extreme climate events for US corn (254 events) and soybeans (250 events) and reports ~22.0% of climate events significantly affect corn returns and ~21.2% affect soybean returns; extreme temperatures and storms produce the largest cumulative abnormal returns, empirical inputs for weather‑related scenario frequency and severity.†https://repository.lsu.edu/gradschool_theses/5992/】.
A thoughtful stress test in this scenario models:
- Partial or total crop loss and resulting basis shifts
- Spikes in local physical prices decoupled from global benchmarks
- Impact on consumable inventory, forward contracts, and logistical challenges
- Knock-on effects: energy prices, input costs, and counterparty reliability
Every trader and asset manager must decide not just the direct impact, but where the initial shock ripples next: contract settlements, margin calls, or credit exposure.
3. Liquidity crisis
Liquidity underpins every successful trade and every timely hedge. But what happens in a drying market? Whether from global shock (like the 2008 financial crisis) or local market freeze, lack of buyers and sellers means prices can gap and margin calls escalate rapidly.
A robust liquidity stress test explores:
- Sharp drop in bid-ask depth for relevant contracts
- Margin requirement increases and collateral shortfall
- Widening of futures-spot basis as OTC and exchange markets decouple
- Effects on portfolio rebalancing and forced unwinds
On the Uhedge platform, detailed analytics and intra-day monitoring support the visibility needed to avoid fire sales and spot margin risks ahead of time.
Mitigating liquidity risk is not only about holding reserve cash. It demands real-time transparency—available through unified dashboards showing position sizes, available credit, and stress-tested scenarios.
4. Counterparty default
Everything in trading relies on trust—until it is tested. Counterparty failure, whether from default or technical glitches, can trigger cascading losses across interconnected positions.
A structured counterparty risk scenario encompasses:
- Instant settlement failure on major open contracts
- Mounted credit exposures (with time lags multiplied under stress)
- Requirement to replace positions at unfavorable market prices
- Cross-default clauses activating in connected agreements
Uhedge strengthens portfolio trust by automating counterparty concentration checks and reporting exposures by name and instrument—making audit and review materially faster and more transparent.
5. Regulatory shock
Rules change fast—sometimes overnight, as in abrupt tax increases, new margin requirements, or position limits. Recent years have seen more intervention as authorities try to manage perceived market excess or systemic risk.
A regulatory stress test typically asks:
- What revaluation arises from a new accounting rule (e.g., changing mark-to-market standards)?
- How does a sudden tax on exports or imports alter trade flows and book equity?
- What forced unwinds may occur if new leverage or position limits are set?
- How will hedge accounting effectiveness be retested and re-documented?
With Uhedge, event-driven scenario creation, automated hedge effectiveness testing, and instant reporting make adapting to new regulations far less disruptive for asset managers and trading houses.
Building and calibrating a scenario: How does it work?
Creating a scenario is part art, part science. Uhedge fuses historical data, proprietary models, and “present danger” assessment.
The critical steps in scenario building include:
- Identification of vulnerabilities: Review all open positions, collateral, and suppliers. Focus is given to exposures with the largest tail risk—those where small probabilities imply heavy damage.
- Frequency and severity estimates: Use empirical data—such as the findings from the LSU thesis on extreme weather’s impact on US crops—to calibrate “realistic but severe” event frequencies, not mere hypotheticals【4:LSU graduate thesis (2024): analyses 1995–2023 extreme climate events for US corn (254 events) and soybeans (250 events) and reports ~22.0% of climate events significantly affect corn returns and ~21.2% affect soybean returns; extreme temperatures and storms produce the largest cumulative abnormal returns, empirical inputs for weather‑related scenario frequency and severity.†https://repository.lsu.edu/gradschool_theses/5992/】.
- Modeling dependencies: Advanced statistical models, including copulas or regime-switching models, capture correlations and the risk of simultaneous extreme moves seen in global crises.
- Projecting secondary effects: For a commodity trader, the second and third-order effects often matter most—usually liquidity, counterparty, currency, or logistics rather than spot price alone.
Uhedge presents these “down-the-line” impacts not as static tables, but through interactive dashboards—integrating stress tests into every-day business practice, not just quarterly or annual review.
Risk measurement techniques: Going beyond historical VaR
Traditional value at risk (VaR) provides a baseline, but commodity portfolios need more.
Key methods for measuring risk under stress include:
- Historical VaR: Looks at actual recent losses, but often fails to predict new or escalating events.
- Scenario analysis: Imposes hypothetical but plausible shocks—essential for climate events, policy changes, and counterparty failures.
- Advanced probability models: GARCH, jump-diffusion, and copula models account for fat tails or correlated disasters. Uhedge’s quant team continuously updates these engines to reflect current macroeconomic and market signals.
- Stress-by-risk-factor: Each risk—basis, FX, volatility, credit, liquidity—gets its own focus before results are unified in a single dashboard.
The core advantage of the Uhedge approach is full integration: audit-traceable testing, real-time updating, and scenario libraries that grow with every new market regime. This is the engine of informed commercial decision-making and credible oversight.
Embedding stress testing in business discipline
Commodity businesses often face risk-accounting burdens: fragmented data, late reconciliations, manual work, and exposure scattered across multiple systems. Uhedge’s unified environment solves this through:
- Real-time position monitoring and margin tracking
- Automated end-of-day reports and performance attribution
- Hedge accounting effectiveness tracking, with documentation ready for audit
- Single-view dashboards aggregating all risk factors (Greeks, volatility, basis)
- Scenario development tools—pre-built for common shocks, customizable for specific business models
The goal: govern exposure, simplify compliance, and provide management with “at-a-glance” assurance.
Moving from stress test results to strategy
A stress test’s value is ultimately found in responses. After a simulated shock, the right process includes:
- Reviewing vulnerabilities and rebalancing hedges
- Optimizing working capital allocation (for example, adjusting cash reserves for margin calls)
- Strengthening counterparty selection or altering contract terms
- Engaging with auditors proactively—showing real scenario outputs and governance steps
- Communicating with stakeholders—proving risk transparency and continuity planning
With automated workflows and scenario documentation, Uhedge helps companies not only comply but compete—protecting margins when peers may be struggling.
Real resilience grows where discipline meets insight.
Benefits beyond compliance: Margin, trust, and opportunity
Why commit to a rigorous stress testing regime? The answer, according to the experience of global commodity teams and the Uhedge model, is multi-fold:
- Increased margin and cash flow predictability: Robust controls reduce risk of sudden losses and improve capital planning.
- Audit readiness: Automated documentation meets stringent IFRS 9 and CPC 38 demands, eliminating much of the manual audit burden.
- Competitive advantage: Proactive stress testing reveals opportunities to capture market inefficiencies when others retreat.
- Institutional trust: Integrated risk governance builds reassurance for partners, lenders, and stakeholders.
- Consistent, data-driven decisions: Discipline enforced by technology complements human experience, eliminating emotional or reactive choices in turbulent periods.
Want more perspectives on protecting your margin and understanding risk in commodity trading? Visit the in-depth article abouthedging in unpredictable markets or browse Uhedge’s educational resources on commodity intelligence.
Uhedge’s “where others see chaos, we see opportunity” mindset is summed up in its client stories—not only managing risk, but turning rigor into value creation. Whether dealing with weather uncertainty or global trade disputes, discipline and scientific approach consistently prove more effective than intuition and hope.
Practical steps to embed stress testing in your organization
Adopting commodity stress testing is a journey, not a one-time project. Success requires:
- Senior leadership buy-in—risk culture starts at the top
- Automated systems for data collection and scenario generation, as provided by Uhedge
- Regular calibration of models using real incident and market data
- Clearly documented responses and risk/return implications of test results
- Continuous training for the team, including scenario reviews and “tabletop” crisis exercises
For businesses looking for a real-world edge, reviewing common mistakes and how to avoid them is fundamental. Uhedge details these insights in common hedging errors and practical solutions.
Want to know how commodity portfolios are tackling the market shifts in 2025? The article on commodity metal markets and resilient hedge strategies provides more detail.
In summary, proactive stress testing, integrated with real-time technology and rigorous analytics, transforms commodity risk management from a defensive activity into a foundation for growth.
Conclusion: Discipline, insight, and the Uhedge advantage
The future of commodity portfolio management will not be defined by those who avoid risk, but by those who prepare for it intelligently. The discipline shown by regular, scenario-driven stress testing changes not only the outcome in a crisis but the confidence with which every day’s trade is made.
It is this focus on insight and discipline—brought to life in Uhedge’s platform and methods—that lets results move from chaos to opportunity. Auditable, actionable, and always informed, these practices serve the agro-financial chain and broader commodity world with the rigor they demand.
Action starts with a single conversation.
Readers interested in transforming their commodity risk strategy—and building a lasting advantage—are encouraged to schedule a diagnostic consultation with Uhedge’s experts for a personalized risk and strategy assessment. Discover how technology and discipline can secure not only compliance, but growth and market leadership.
Frequently asked questions (FAQ)
What is commodity stress testing?
Commodity stress testing refers to the systematic evaluation of a portfolio’s resilience to plausible adverse events affecting commodities, such as market shocks, weather disasters, liquidity freezes, or regulatory changes. It involves scenario construction and quantitative modeling to forecast the impact of extreme but realistic conditions on cash flows, positions, and risk exposures.
How does stress testing impact commodity markets?
Stress testing in commodity markets helps identify hidden vulnerabilities in trading or asset management strategies, promotes better decision-making, and encourages proactive adjustments ahead of market turmoil. For organizations, this practice builds confidence with stakeholders and ensures compliance with regulatory requirements, strengthening operational and financial resilience.
What are common scenarios in stress tests?
Common stress scenarios include geopolitical disruptions, extreme weather events, sudden liquidity crises, counterparty defaults, and regulatory or tax shocks. Each is tailored to reflect the most significant and plausible risks relevant to the organization’s exposure, often combining multiple simultaneous shocks to test the boundaries of risk management systems.
Why is stress testing important for commodities?
Stress testing is vital because commodity markets are inherently more volatile and sensitive to global events than many other asset classes. Regular stress tests reveal exposures to rare but catastrophic events, support robust margin and liquidity planning, and help organizations avoid losses (or seize opportunities) that may not be captured by conventional value-at-risk metrics.
How can I perform a commodity stress test?
Performing a commodity stress test involves collecting position and risk data, identifying plausible stress scenarios, assigning severity and frequency to those scenarios, and running simulations to estimate portfolio impact. Platforms like Uhedge offer advanced tools and automation for integrating these steps into daily practice, ensuring every result is auditable, actionable, and aligned with both hedge accounting and governance requirements.