
Derivative valuation is the discipline of turning a contract into a current economic value that treasury, risk, accounting, and management can actually use. For commodity producers, processors, exporters, and industrial buyers, that value is not just a model output: it shapes hedge decisions, margin planning, audit evidence, and P&L interpretation. If your exposures sit across physical inventory, futures, options, swaps, and FX, the right question is not only how to price the instrument, but how to value it in the context of the whole book.
That is where many teams struggle. A mathematically correct price can still be operationally wrong if it ignores basis, volatility regime shifts, funding pressure, or fragmented data. Uhedge approaches the problem from a physical plus financial perspective, combining pricing, mark to market, risk decomposition, and accounting support in one auditable environment.
Key takeaways for treasury and risk teams
- Fair value is contextual: the same contract can look cheap or expensive depending on volatility, basis, funding, and hedge objective.
- Model choice follows instrument design: forwards, futures, options, swaps, and exotic structures cannot be valued with a single shortcut.
- Inputs matter more than formulas alone: bad curves, stale volatility, or missing basis assumptions can distort results faster than a weak equation.
- Independent controls are essential: valuation should feed mark to market, limit monitoring, margin management, and governance, not sit in a spreadsheet silo.
- Commodity books need physical integration: location basis, freight, quality, and FX often explain more P&L than the headline futures move.
What does derivative valuation actually mean in practice?
In practice, valuation means estimating what a contract is worth today under current market conditions and contract terms. That sounds simple, but the operational goal is broader: you need a value that supports trading decisions, daily P&L, exposure measurement, collateral planning, and accounting treatment.
For a treasury team, the usable number is usually a mark to market that can be reconciled every day. For a hedge committee, it is a price that can be compared with alternative structures. For finance, it is evidence that the position can be documented consistently. A more detailed guide for risk and treasury teams helps frame those different uses.
The key mistake is to treat valuation as an isolated quant exercise. In real commodity and FX hedging, value only becomes decision useful when it is connected to the exposure being protected, the cash flow profile of the company, and the controls around the position.
Which methods are used to value derivatives?
Most instruments fall into four practical valuation families. The correct choice depends on payoff shape, path dependence, optionality, and the quality of observable market inputs.
| Method | Best suited for | Main strength | Main limitation |
|---|---|---|---|
| Discounted cash flow | Forwards, swaps, simple linear hedges | Transparent and easy to reconcile | Limited for nonlinear payoffs |
| Closed form option models | Vanilla options | Fast and consistent for daily use | Depends heavily on volatility assumptions |
| Lattice methods | Early exercise and some structured options | Flexible treatment of exercise features | Can become cumbersome for complex structures |
| Monte Carlo simulation | Path dependent and exotic contracts | Handles complex payoff logic | More demanding in data, calibration, and governance |
Teams dealing with more tailored structures should also understand where each model breaks. This is especially true for accumulators, fences, Asians, and other payoffs that mix optionality with operational hedge objectives. A useful companion is this overview of pricing models, market fit, and pitfalls.
How do you estimate the value of a derivative?
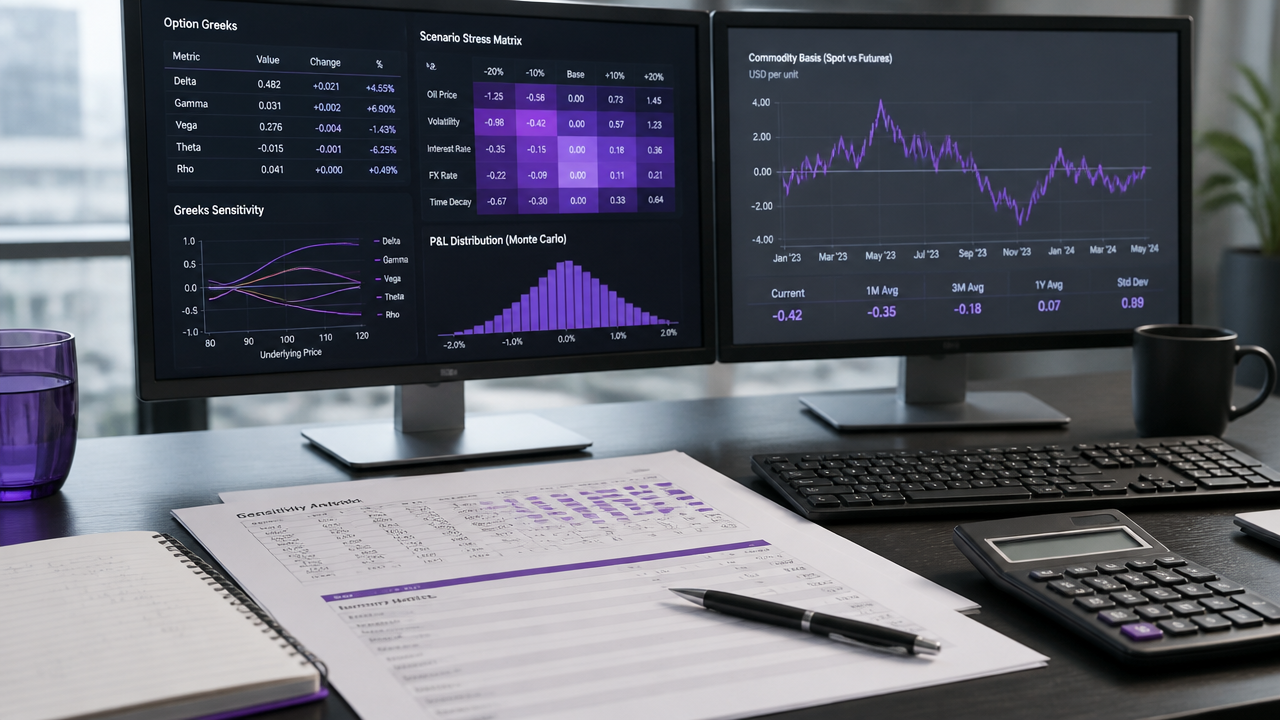
You estimate value by combining the contract payoff with current market inputs. For most books, the core drivers are straightforward, but their interaction is what creates valuation risk.
The essential inputs are usually these
- Spot or reference price of the underlying
- Forward curve or expected settlement profile
- Volatility, implied or modeled
- Interest rates and discount factors
- Time to maturity and settlement calendar
- FX, when the hedge and exposure sit in different currencies
- Basis, freight, quality differentials, or local premiums for physical commodities
- Counterparty and margin terms, when funding and credit matter
This is why two firms with the same option can carry different operational values. One may hedge soybean purchases in a location with stable basis. Another may face shifting regional premiums, freight changes, and BRL versus USD exposure. If you ignore those layers, the model price may be elegant but strategically misleading. That is why basis risk in treasury and asset management deserves to sit inside the valuation discussion, not outside it.
Where do derivatives get their value?
Derivatives get their value from both the underlying market and the contract structure. The underlying provides the economic engine, while the contract defines how gains and losses are transferred between parties.
For a future or swap, value comes mainly from the difference between the contracted level and the current forward market. For an option, value also reflects time, expected volatility, strike level, and payoff asymmetry. For a commodity hedge, local basis can materially change the economics even when the reference exchange price barely moves.
That is why Uhedge treats physical and financial books together. Its CTRM platform was built to register, monitor, and report physical and financial positions in one environment, which helps risk teams avoid the classic error of valuing the derivative correctly while valuing the hedge context badly. In day to day operations, that integrated view is often more useful than a stand alone pricing sheet. Readers interested in the broader architecture can explore how CTRM software supports the trade lifecycle.
Why mark to market is not the same as a one time price check
Mark to market is the control layer that turns valuation into management. A trade price agreed on day one may be commercially fair, but the business still needs a daily revaluation process to understand P&L, liquidity, and hedge effectiveness.
That daily process matters because valuation errors compound operationally. A stale curve can distort hedge performance, a missed volatility shift can understate option risk, and weak counterparty monitoring can hide funding pressure until margin calls arrive. Good governance requires daily consolidation, historical evolution, and sensitivity tracking, not just a theoretical fair value.
Uhedge's platform reflects this operating reality with consolidated mark to market by book, end of day reporting, counterparty monitoring, and FCM cash and margin visibility. If your current process still depends on fragmented spreadsheets, a practical next step is to review real time mark to market monitoring.
What makes commodity and FX books harder to value than plain vanilla textbooks suggest?
Commodity and FX books are harder because the risk is rarely one dimensional. A grain exporter can be exposed to futures, local basis, freight, storage timing, and USD cash flows at the same time. A food manufacturer may hedge imported inputs with options yet still face local procurement mismatches.
In those books, the most useful valuation process does three things well:
- separates price, FX, volatility, and basis drivers clearly,
- shows sensitivity by factor rather than only a final number,
- connects the derivative to the physical exposure and liquidity plan.
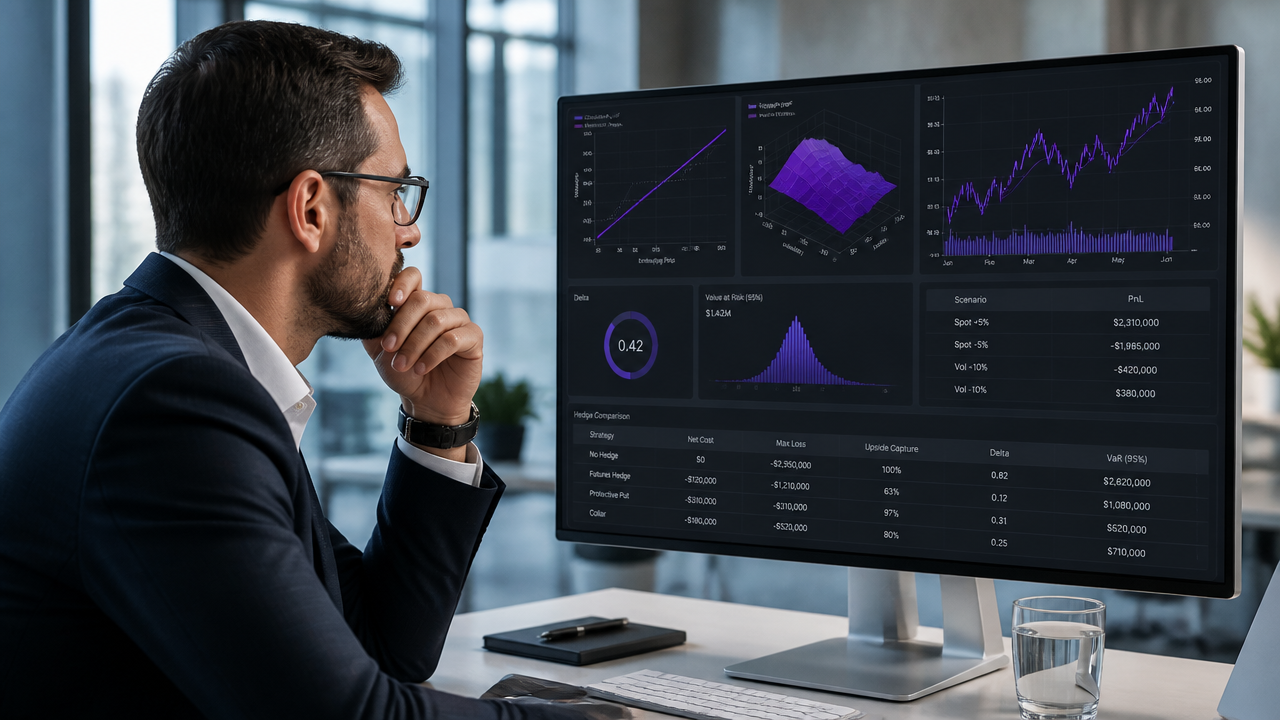
Uhedge was designed for exactly this kind of multi leg problem. The platform supports vanilla and exotic structures, OTC replication, Greeks by position, volatility surface analysis, factor based VaR, stress testing, and a three leg hedge view that can separate derivatives, physical basis, and FX. For firms building hedge programs across commodities and currencies, this perspective is close to the operational reality described in corporate FX hedging and risk control.
How do model risk, basis risk, and audit demands affect valuation quality?
Valuation quality is determined as much by governance as by mathematics. A strong model can still produce weak decisions when assumptions are undocumented, market data is inconsistent, or no one can explain the move from one day to the next.
The three recurring weak points are:
- Model risk: using a convenient model outside its proper payoff or market regime.
- Basis risk: assuming the exchange contract offsets the local physical exposure more closely than it really does.
- Audit risk: failing to keep a clear trail from designation and pricing assumptions to daily valuation and effectiveness evidence.
This is where Uhedge's auditable workflow becomes strategically important. The platform combines pricing and risk controls with support for IFRS 9 and CPC 38 hedge accounting, including effectiveness testing and designation reporting. For companies that need discipline from trade capture through documentation, the most relevant parallel topic is risk and compliance in a hedge management system.
When does better valuation create economic value, not just better reporting?
Better valuation creates economic value when it improves hedge selection, cuts avoidable cost, and prevents liquidity surprises. That is especially relevant for firms that still rely heavily on bank quotes without an independent framework to judge structure quality, embedded spread, or timing.
Uhedge positions itself as a conflict free extension of the client's operation, with an alignment model built around client outcomes rather than hidden spreads or opaque commissions. According to the company's reference materials, that approach can reduce hedge costs by up to 70 percent in cases where traditional intermediation had been eroding margin. More importantly, it gives treasury teams a unified way to compare structures, monitor daily changes, and document decisions in one place.
If valuation is treated as a living process rather than a one off formula, it becomes a practical source of margin protection, not just an accounting requirement.
Frequently asked questions
What is the value of a derivative?
A derivative is usually valued as the present value of its expected future cash flows under current market conditions. In practice, that means combining observable inputs such as the underlying price, forward curve, volatility, interest rates, time to maturity, and contract terms, then applying the model that fits the instrument.
How do you estimate the value of a derivative?
You estimate a derivative's value by matching the method to the contract. For linear products such as forwards and swaps, discounted cash flow is often enough. For options, valuation usually requires an option model plus volatility assumptions, time value, and sensitivity analysis. Complex structures may need simulation and independent controls.
Where do derivatives get their value?
Derivatives get their value from an underlying risk factor and from the structure of the contract itself. The main sources are spot and forward prices, volatility, interest rates, time to expiry, basis, FX, and counterparty terms. For commodity hedgers, local basis and logistics can be as important as the exchange price.
What are the main methods used to value derivatives?
The four practical families are discounted cash flow, closed form option models, lattice methods such as binomial trees, and simulation methods such as Monte Carlo. Teams often use more than one: one model for primary pricing, another for validation, and a separate process for mark to market and control.
What did Warren Buffett mean when he warned about derivatives?
Warren Buffett famously warned that derivatives can become dangerous when they are opaque, highly leveraged, or poorly controlled. The useful lesson for corporate hedgers is not to avoid every derivative, but to avoid positions they cannot price, monitor, document, or fund through volatility and margin stress.