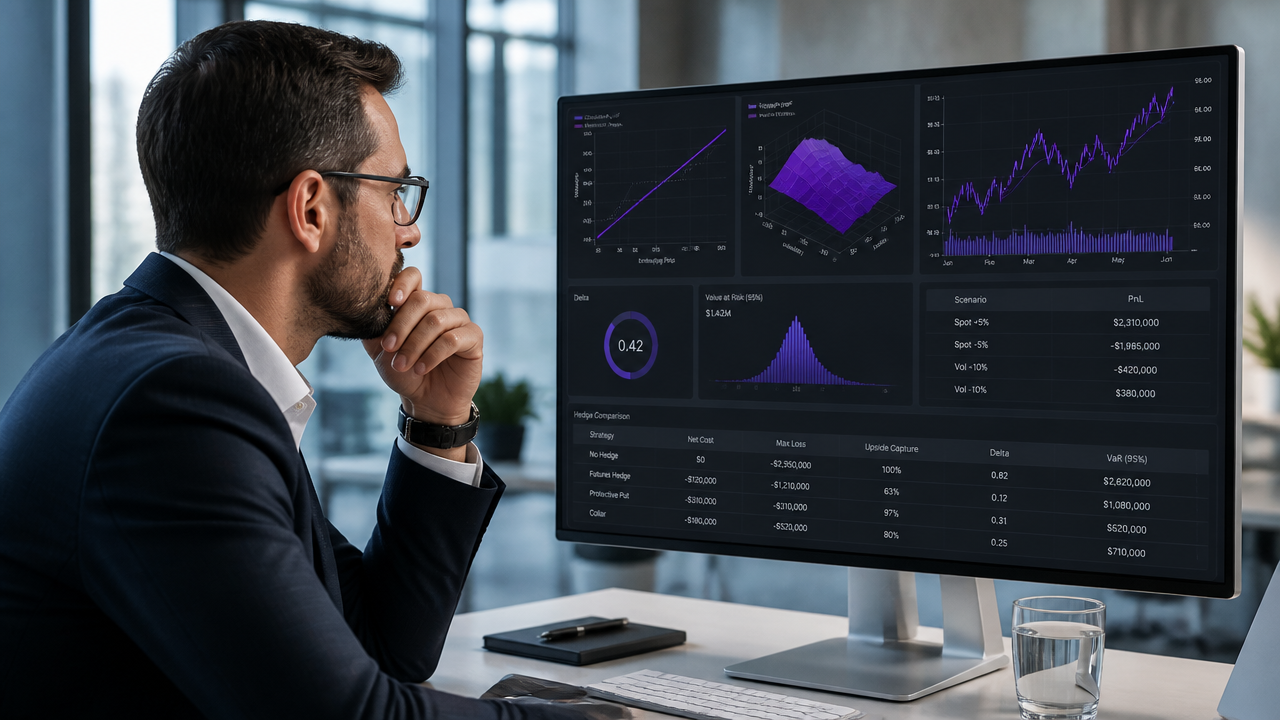

A derivative margin call is not just a trading event, it is a liquidity event. If futures, options, or swaps move against an open hedge, the broker, clearing member, or counterparty can demand more collateral within hours. For producers, cooperatives, mills, importers, and treasury teams, the real challenge is not only pricing the hedge correctly, but making sure cash is available when markets turn.
This matters most for companies that hedge real exposures in commodities, FX, or rates. A hedge can protect commercial margins over the life of the exposure and still create short term cash pressure on the way. That is why good risk management connects market exposure, mark to market, basis, and collateral planning in one operating view.
Key points at a glance
- A margin call is a funding requirement, triggered when losses or higher risk assumptions reduce collateral coverage.
- Initial margin and variation margin are different: one is posted to open or maintain the position, the other reflects mark to market losses and gains.
- Good hedges can still create painful cash drains if treasury plans only for price risk and ignores liquidity risk.
- Physical exposure matters: basis, freight, taxes, and timing mismatches can make a hedge look safe on paper while cash needs rise in practice.
- Control improves when risk is unified across exposure mapping, mark to market, stress testing, and collateral monitoring.
What is margin in derivatives?
In derivatives, margin is collateral posted to support an open position. It exists because counterparties and clearing houses need protection against the risk that one side cannot pay if markets move sharply.
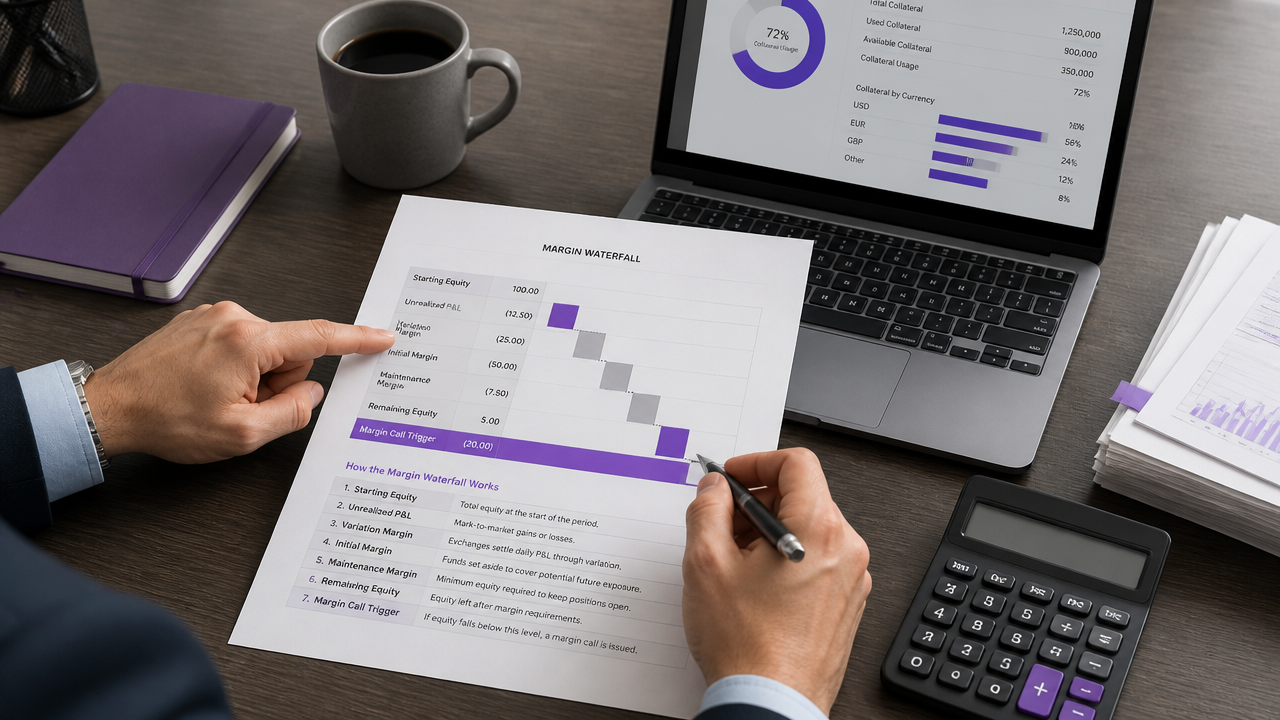
There are three moving parts. Initial margin is the opening buffer. Variation margin is the daily, and sometimes intraday, cash settlement of mark to market gains and losses. Maintenance logic is the threshold that determines when available collateral is no longer enough and more must be posted.
That is why a margin call should never be treated as a mere broker message. It is the point where market risk becomes an operational cash requirement. Teams that already work with real time mark to market monitoring usually react faster because they see the shortfall building before the formal call arrives.
What triggers a margin call in practice?
The direct trigger is simple: your collateral becomes insufficient for the risk or loss in the position. The underlying causes, however, are broader than a single adverse price move.
Most calls come from one or more of these situations:
- the market moves against the hedge or speculative position
- volatility rises, increasing required margin even if price barely changes
- offsets between positions weaken or disappear
- an exchange or counterparty tightens risk parameters
- intraday moves breach internal or external limits
This is especially important in commodities and FX. A company may be directionally right over the quarter and still face a sharp collateral demand this week. That is one reason firms using portfolio level stress testing tend to manage hedge programs more calmly: they prepare for path risk, not only end point risk.
Why are margin calls risky even when the hedge is correct?
Margin calls are risky because they attack liquidity before the commercial result is realized. A grain processor, sugar mill, exporter, or food manufacturer may be economically hedged, but the physical sale, inventory conversion, or invoice collection often happens later than the cash call.
That timing mismatch explains why treasury teams sometimes confuse a good hedge with a bad experience. The hedge may still protect gross margin over the season, yet the company feels pressure because cash leaves today while the offsetting physical benefit appears weeks later.
For firms exposed to local basis and physical logistics, the picture gets harder. The futures leg may move one way while local basis, freight, or tax effects move differently. A practical guide to basis risk in hedging decisions helps clarify why collateral pain can coexist with a sensible commercial hedge.
How treasury should think about initial margin, variation margin, and headroom
The safest approach is to manage derivatives through a liquidity ladder, not only a price view. Treasury should know how much cash is committed on day one, how much can move daily, and what reserve remains under stress.
| Component | What it does | Main treasury question |
|---|---|---|
| Initial margin | Collateral posted to establish or maintain exposure | How much cash is tied up from the start? |
| Variation margin | Cash paid or received as positions are marked to market | How large can daily calls become? |
| Collateral headroom | Excess funding capacity beyond current needs | How long can we absorb volatility without forced action? |
| Eligible collateral mix | Assets accepted by broker or counterparty | What can be posted quickly without hurting operations? |
This is where process matters. Uhedge describes its platform as a CTRM environment that unifies physical and financial positions, consolidated mark to market, counterparty monitoring, and FCM cash composition, including automatic margin call alerts. For treasury teams, that unified view is more valuable than a standalone pricing screen because collateral stress rarely comes from one instrument in isolation.
How much liquidity buffer is enough?
There is no universal number, but there is a robust method. A company should size its margin buffer against stressed but plausible moves in price, volatility, and basis, then compare that requirement with actual liquid resources and credit lines.
A practical process usually looks like this:
- map net physical and financial exposure by tenor and risk factor
- estimate daily and cumulative mark to market sensitivity
- run stress scenarios for sharp adverse moves and volatility spikes
- add operational friction, such as settlement timing and banking cutoffs
- set a minimum liquidity reserve and escalation thresholds
Teams that already work with structured stress test routines are better positioned to answer the question management really cares about: how many bad sessions can we withstand before the hedge starts dictating business decisions?
Can margin calls be reduced without abandoning the hedge?
Yes, but only if the company understands which part of the problem is structural and which part is self inflicted. Some calls are inevitable in volatile markets. Others come from poor hedge sizing, weak instrument selection, or fragmented monitoring.
Companies usually improve outcomes by:
- matching hedge size more closely to net exposure instead of gross exposure
- staggering maturities instead of concentrating one large entry point
- comparing futures, options, and OTC structures by liquidity profile, not only premium
- monitoring Greeks and volatility when options are involved
- keeping basis and physical coverage in the same decision framework
Uhedge positions this as a combined trading, pricing, and risk discipline problem. Its platform supports vanilla and more complex structures, OTC replication, VaR by risk factor, stress testing, and hedge accounting support. In practical terms, that means treasury can compare strategies not only by expected protection, but also by potential collateral behavior, which is often the missing layer in hedge discussions.
That is also why a modern CTRM workflow for commodity risk matters. When exposure planning, pricing, and collateral control live in separate spreadsheets, margin calls feel sudden. When they sit in one auditable environment, they become measurable and governable.
What should a company do the moment a margin call arrives?
The first priority is operational, not intellectual: confirm the amount, deadline, eligible collateral, and current exposure. Only after the call is clearly validated should the team decide whether to post, resize, or replace the hedge.
A disciplined response usually follows this order:
- verify the calculation and settlement deadline
- reconcile the mark to market with internal books
- check whether basis or physical offsets are expected to monetize soon
- compare the call with preapproved liquidity lines
- decide whether to post collateral, reduce exposure, or restructure the position
If this routine feels too manual, that is often the deeper issue. Uhedge was built for companies that need institutional style control over commodities, FX, and rates without relying on scattered systems or opaque bank pricing. The value is not avoiding every call, because no platform can stop volatility, but anticipating funding pressure early enough to preserve commercial decision quality.
Frequently asked questions
What is margin in derivatives?
A margin call in derivatives is a request to post more cash or eligible collateral after market moves increase losses or required margin. It is common in futures, cleared options, and some OTC structures. The goal is to keep the position properly funded and reduce counterparty risk.
Are margin calls risky?
Yes, margin calls can be risky because they turn market volatility into an immediate cash need. The position may still be economically sound over time, but the liquidity pressure arrives now. If the company cannot post collateral quickly, it may be forced to reduce positions at the worst moment.
How is a margin call amount calculated?
A margin call is usually calculated as the gap between available collateral and the required margin after mark to market. In practice, the amount depends on price moves, position size, volatility, offsets, and exchange or counterparty rules. That is why treasury teams monitor both P and L and collateral headroom together.
Do all derivative contracts generate margin calls?
Not always. Many OTC derivatives are collateralized bilaterally, while some options are fully paid upfront and do not generate the same daily cash flow pattern as futures. The contract terms matter. Treasury teams should review thresholds, eligible collateral, cure periods, and close out rules before trading.
What should a company do after receiving a margin call?
Meet the call first, then decide whether to resize the hedge. Companies usually have three levers: post cash, deliver eligible collateral, or cut exposure. The right choice depends on whether the price move is temporary noise, a structural shift, or a sign that the original hedge ratio was too aggressive.